info@sriyaent.com

 +91 9825375241
India’s FDI Clarifications on Land-Border Investments: What Overseas Firms and M&A Dealmakers Must Know Key…
The Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026 (FAST-DS 2026) offers a dedicated one-time compliance window for individuals and small businesses to regularize undisclosed foreign holdings and rectify past Schedule FA omissions.
Operating from 16 August 2026 to 31 December 2026, FAST-DS provides statutory relief under the The Government of India (‘GOI’) introduced “The Foreign Assets of Small Taxpayers – Disclosure Scheme, 2026” (“FAST-DS, 2026’/‘the Scheme”), through the Finance Act, 2026. However, taxpayers facing concurrent Foreign Exchange Management Act (FEMA) breaches require a coordinated strategy to achieve full legal and financial immunity.
Introduced under Chapter IV (Sections 130–144) of the Finance Act, 2026, FAST-DS allows eligible Resident and Ordinarily Resident (ROR) taxpayers to voluntarily report overseas assets—such as foreign bank accounts, ESOPs/RSUs, offshore brokerage accounts, and foreign immovable properties—held as of the valuation date of 31 March 2026.
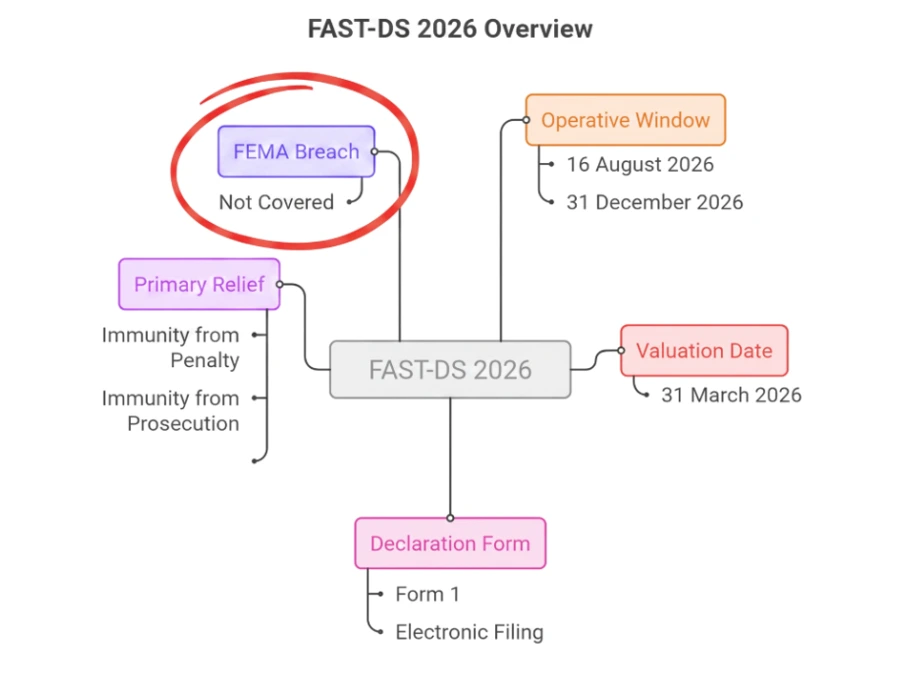
FAST-DS 2026: The Two Disclosure Routes
The scheme distinguishes between untaxed offshore wealth and procedural reporting omissions:
| Feature | Route 1: Undisclosed Foreign Income & Assets | Route 2: Procedural Non-Reporting / Schedule FA Omission |
| Eligibility Threshold | Aggregate fair market value (FMV) up to ₹1 Crore | Aggregate FMV up to ₹5 Crore |
| Qualifying Assets | Untaxed foreign income or unexplained overseas assets | Assets acquired from previously taxed income or while non-resident (NRI/RNOR status) |
| Applicable Tax / Fee | 60% total (30% base tax + 100% additional surcharge) | Flat fee of ₹1,00,000 per eligible asset stream |
| Typical Use Case | Undeclared foreign consulting income, offshore earnings | Unreported foreign bank accounts, tech RSUs/ESOPs, returned NRI holdings |
Have Foreign Asset or FEMA Compliance Concerns? Contact us today for a compliance assessment.
Why FAST-DS Alone Is Not Enough?
While FAST-DS grants explicit immunity against penalties and criminal prosecution, it does not automatically grant immunity under FEMA, 1999.
- Unregularized Foreign Accounts: Holding foreign bank accounts after returning to India beyond permitted timelines without converting to RFC (Resident Foreign Currency) accounts.
- ODI / OPI Non-Compliance: Unreported equity stakes or direct investments in foreign entities without requisite Reserve Bank of India (RBI) filing or UIN generation.
- LRS Limit Breaches: Capital account transactions that deviated from Liberalised Remittance Scheme (LRS) reporting norms.
- Tax Immunity ≠ Foreign Exchange Immunity
- Declaration under FAST-DS resolves Income Tax liabilities.
- Parallel regularisation or Compounding with RBI is essential to resolve FEMA contraventions.
While the FAST-DS 2026 window protects taxpayers, it provides zero statutory protection against the Foreign Exchange Management Act (FEMA), 1999. Holding foreign assets, overseas bank accounts, or foreign securities without adhering to Reserve Bank of India (RBI) guidelines constitutes a regulatory breach.
Failing to address these contraventions exposes individuals and entities to Section 13 adjudication proceedings, which carry penalties up to 300% of the contravened sum, along with potential Enforcement Directorate (ED) scrutiny.
How Sriya Enterprise Can Help?
Navigating FEMA disclosures requires technical precision across both direct tax and foreign exchange law. Sriya Enterprise provides end-to-end advisory and compliance solutions -FEMA & RBI Compounding Support: Drafting and executing compounding petitions before the RBI to eliminate foreign exchange liabilities.
Frequently Asked Questions
FAST-DS 2026 is a one-time disclosure scheme that allows eligible taxpayers to voluntarily disclose certain undisclosed or previously unreported foreign assets and holdings.
The scheme is intended for eligible Resident and Ordinarily Resident (ROR) taxpayers who meet the prescribed conditions and asset-value limits.
No. FAST-DS tax relief does not automatically provide immunity from FEMA violations. Separate FEMA regularization or RBI compounding may be required.
Eligible foreign bank accounts may be covered depending on the nature of the asset, its source, the taxpayer’s status, and the applicable conditions of the scheme.
An unreported ODI, OPI, or other overseas investment may require separate FEMA compliance or regularization with the RBI through the applicable Authorized Dealer (AD) bank.
FAST-DS addresses applicable income-tax disclosure issues. LRS-related FEMA contraventions require separate assessment and regularization under FEMA.
Conclusion
FAST-DS 2026 provides a valuable opportunity for eligible taxpayers to disclose undisclosed or previously unreported foreign assets within the specified window. However, tax disclosure under FAST-DS does not automatically resolve FEMA violations. Individuals and businesses should separately review foreign bank accounts, overseas investments, LRS transactions, and other foreign assets for FEMA and RBI compliance. Taking timely action can help reduce regulatory risks and ensure a smoother path toward regularization or compounding.
Related Posts