info@sriyaent.com

 +91 9825375241
India’s robust macroeconomic trajectory continues to attract significant global capital. For foreign entities and Indian…
A persistent rumor has been quietly circulating among corporate finance desks, export councils, and cross-border businesses: FEMA is becoming a toothless, orphan regulation.
With the Reserve Bank of India (RBI) systematically delegating operational powers to Authorised Dealer (AD) Category-I banks, dismantling legacy paperwork, and phasing in structural overhauls effective 1st October 2026, many have jumped to the conclusion that cross-border compliance is relaxing.
The assumption seems logical at a glance: if you no longer need regional RBI approvals for standard transactions, and routine clerical bottlenecks are being eliminated, surely compliance is taking a back seat?
That assumption is a dangerous miscalculation.
FEMA isn’t going away on 1st October 2026—it is entering an automated, zero-tolerance era. The transition taking place is not deregulation; it is decentralization backed by algorithmic enforcement.
1. “Bank Discretion” Actually Means “Bank Liability”
The biggest misunderstanding in the market centers around AD bank discretion. Many promoters and finance heads assume that because the local branch manager knows their business, transactions will flow with fewer questions.
In institutional banking, however, discretion translates directly into liability.
When the regulator shifts authority to commercial banks, it simultaneously holds those banks accountable during statutory supervisory reviews. Banks do not respond to delegated power with casual leniency; they respond with defensive, rigid, and Board-approved Standard Operating Procedures (SOPs).
A relationship manager cannot “overlook” a non-standard remittance route or an unregularized export entry. Their internal compliance engine requires every supporting document to match statutory checklists down to the invoice, HS code, and beneficial ownership line. If documentation falls short, the bank’s default position is self-preservation: halt the transaction.
2. The Shift from Paper Audits to Algorithmic Hard-Stops
Under the legacy framework, non-compliance was a slow burn. Discrepancies were caught months (or years) later during periodic regulatory inspections, manual scrutiny, or tax audits.
Today, compliance is digital, silent, and instantaneous:
- Interconnected Data Pipelines: The days of reporting in silos are over. Customs (ICEGATE), Goods and Services Tax (GSTN), and central banking ledgers (EDPMS and IDPMS) are directly interconnected. A mismatch between a shipping bill, a GST invoice, and inward remittances flags immediately.
- System Hard-Stops: When an export entry exceeds the realization window, the alert isn’t generated by a clerk—it is triggered by an automated algorithm.
- Operational Gridlock: Once an account is system-flagged for chronic unreconciled entries, the consequences are immediate. Trade lines tighten, advance remittances face mandatory scrutiny, and transactions can be restricted to 100% advance payments or irrevocable Letters of Credit (LCs). No branch executive can manually override a central engine block.
Need help with FEMA Compliance? Contact Sriya Enterprise for expert guidance on FEMA Regulations, RBI requirements, EDPMS and IDPMS.
3. What the 1st October 2026 Overhaul Really Means
The new regulatory architecture under the Foreign Exchange Management (Export and Import of Goods and Services) Regulations replaces rigid procedural bottlenecks with commercial speed, but sharpens the penalty for sloppy ledger hygiene:
| Old Compliance Era | The Post-1st October 2026 Reality |
| Transaction-Level Scrutiny via separate statutory filings (e.g., standalone SOFTEX forms for software). | Unified Export Declaration Framework (EDF) directly tied to banking reconciliation. |
| Paper-Driven Discretion requiring formal RBI compounding or permissions for routine operational issues. | Decentralized AD Bank SOPs that place full compliance risk and proof on the business entity. |
| Clerical Tracking of realization overdue files across physical bank desks. | Automated Alerts & Freezes across integrated EDPMS/IDPMS networks for persistent defaults. |
| Endless Open Vouchers clogging banking records for negligible trade entries. | Streamlined Clean-Up Powers allowing banks to write off minor amounts, freeing resources to audit high-value exposures. |
4. Why the Need for FEMA Guidance Is at an All-Time High
In the legacy era, cross-border consultants were often treated as clerical liaisons—people hired to walk physical files through regional RBI desks or STPI offices.
As those physical touchpoints disappear, many ask: “If everything is routed through my bank’s portal, why do I need a FEMA consultant?”
The answer lies in the gap between business operations and bank compliance desks:
- Banks Are Processors, Not Advisors: Your AD bank will gladly highlight what is wrong or freeze an entry that doesn’t meet SOP criteria. They will not design the operational fix, reconcile historical data mismatches, or structure the transaction to fit regulatory boundaries.
- Navigating Divergent Bank SOPs: Because powers are delegated, Bank A and Bank B may interpret RBI guidelines differently within their respective internal manuals. When complex commercial structures—such as third-party payments, SaaS export reconciliations, merchanting trade, or overseas subsidiaries—hit a compliance roadblock, businesses require technical advocacy to satisfy bank credit committees.
- Preventative Audit vs. Post-Mortem Rectification: Repairing compounding issues with the regulator after banking facilities have been frozen is expensive, disruptive, and reputation-damaging. Modern cross-border trade demands pre-emptive health checks and continuous ledger reconciliation.
The Takeaway
FEMA is neither dead nor an orphan framework. It has simply shed its visible administrative skin to become an embedded, real-time banking standard.
Businesses that treat 1st October 2026 as a relaxation of rules will inevitably face operational friction. Those that treat it as a call for tighter digital hygiene, proactive bank alignment, and robust cross-border governance will find their global trade faster and more scalable than ever before.
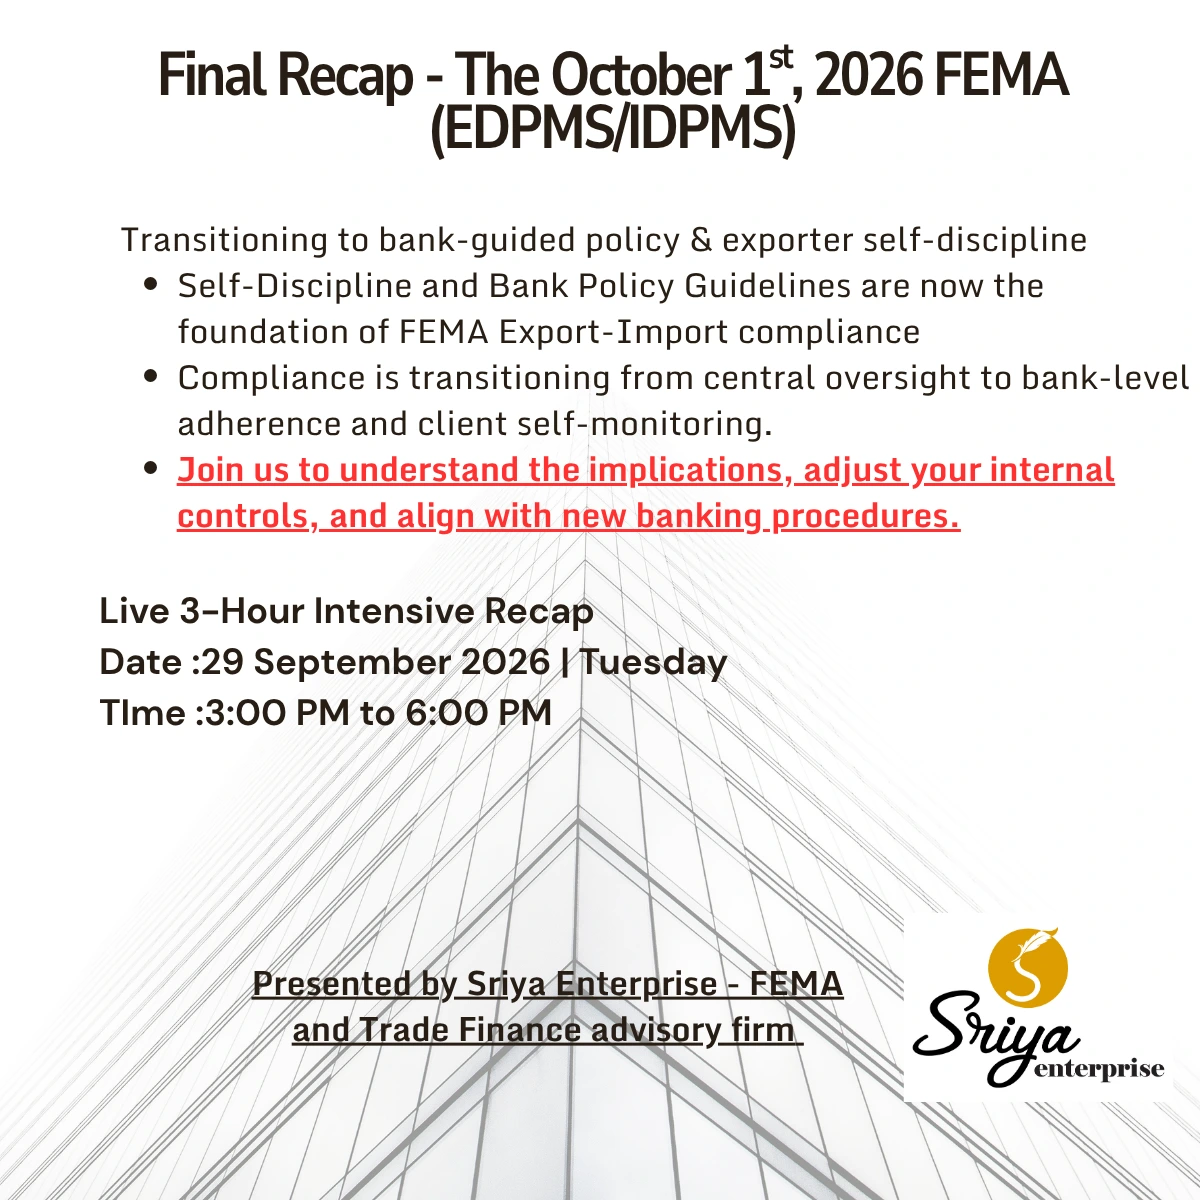
Preparing your finance and treasury teams for the 1st October 2026 transition? Ensure your internal EDPMS/IDPMS reconciliations and banking SOPs are fully aligned before the automated checks kick in.
Frequently Asked Questions
No. The transition does not mean that FEMA compliance is disappearing. The changes are aimed at simplifying procedures, delegating certain operational responsibilities, and making cross-border transactions more efficient while maintaining regulatory oversight.
The regulatory framework is moving toward a more streamlined and decentralized compliance model, with greater operational responsibility for Authorised Dealer (AD) banks and increased reliance on digital processes and banking systems.
EDPMS and IDPMS help banks and businesses track export and import transactions, including realization, payment, and outstanding entries. Unreconciled or overdue transactions can create compliance and operational issues.
Yes. Banks are responsible for processing foreign exchange transactions in accordance with applicable regulations and their internal compliance procedures. Transactions may require additional documentation, clarification, or review when compliance requirements are not satisfied.
Conclusion
FEMA is not disappearing from India’s cross-border regulatory framework; it is evolving into a more decentralized and digitally driven system. From 1st October 2026, greater reliance on AD banks, integrated systems, and automated monitoring will make accurate documentation, timely reconciliation, and transaction-level compliance more important than ever.
For businesses engaged in international trade, the focus should shift from reacting to compliance issues to preventing them. Reviewing EDPMS/IDPMS records, aligning with bank SOPs, and maintaining strong internal FEMA controls can help businesses navigate the transition smoothly while keeping their cross-border operations efficient and compliant.
Related Posts